Course 01Université Sorbonne Paris Nord
Dynamic Optimization and Monte Carlo Methods in Python
Master 2 MBFA – Financial Engineering and ModellingMaster 2 MBFA – Insurance Engineering
Seven sessions to learn to compute with chance, and to prove that you are right.
ExcerptSession 1 · Computing with chance
The course plan
Seven sessions, four tabs each.
-
 1Computing with chance How many samples does it take to be right?
-
Session 1 · graded, in groups
Graded assignment (in French) -
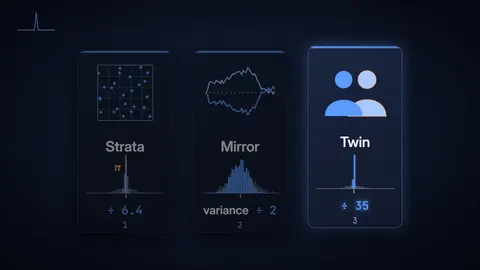 2Less variance, same budget Divide the error by thirty without a single extra sample?
Coming soon
-
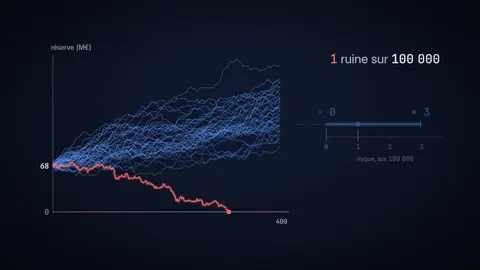 3Aim where it counts How do you measure a ruin that never happens in your simulations?
Coming soon
-
 4Working backwards Why is the best decision computed by starting from the end?
Coming soon
-
 5The contraction Why does the iteration always converge?
Coming soon
-
 6Exercise or wait What is the right to change your mind worth?
Coming soon
-
 7Learning to decide Can you learn a good decision without knowing the model?
Coming soon
-
The experiments from the films, to redo yourself
The lab
The method
Every session is watched, read, and redone.
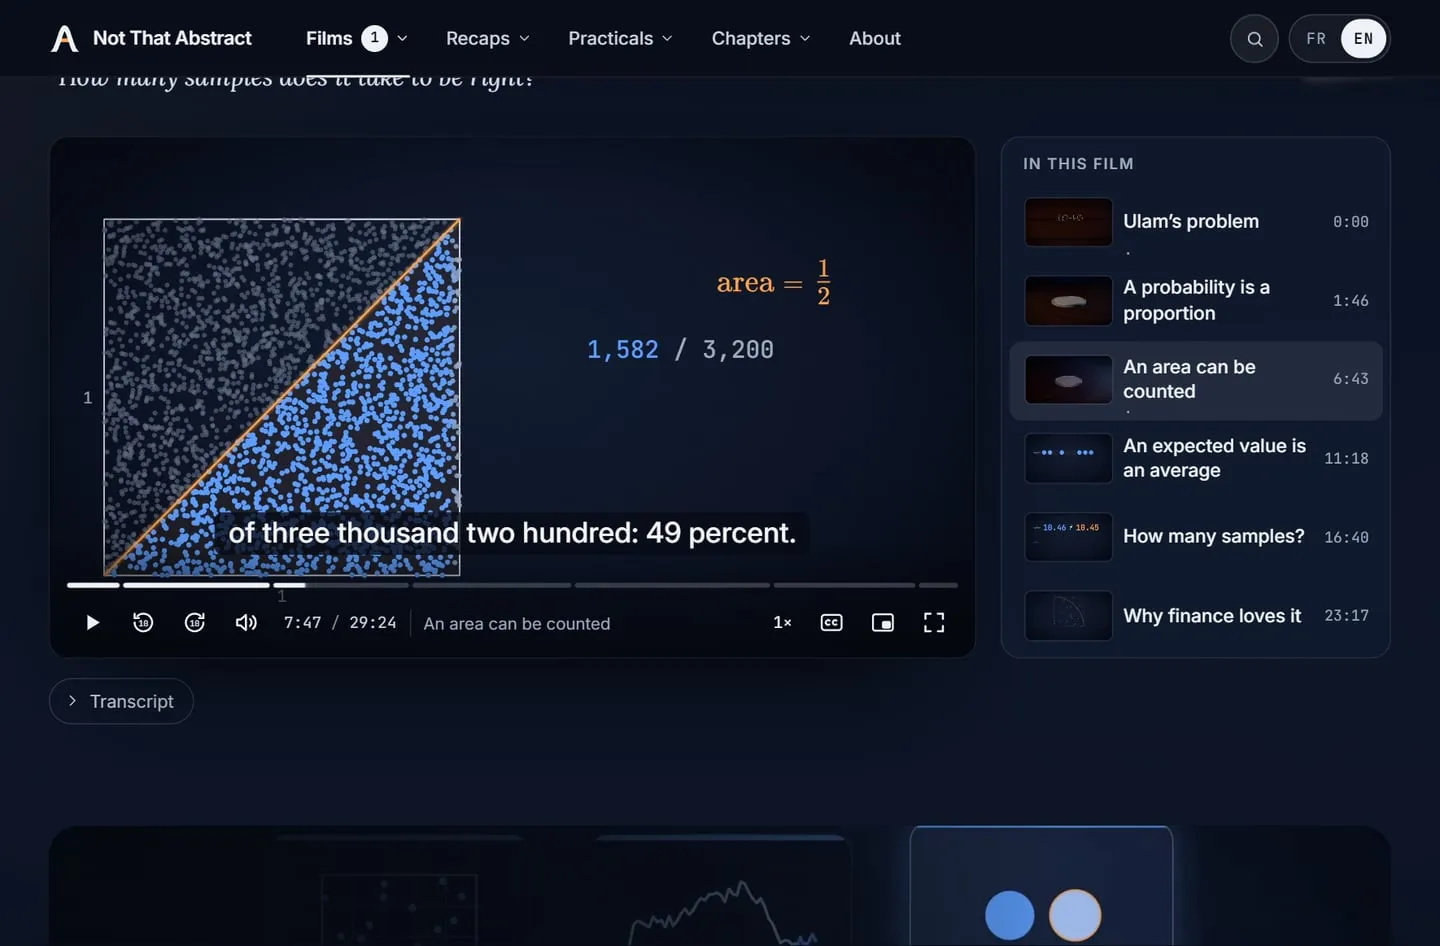
Courses to watch, to read and to redo yourself.
Free, no account, in French and in English.